
What is blockchain technology?
Blockchain is a decentralized digital ledger that securely stores records across a network of computers in a way that is transparent, immutable, and resistant to tampering. Each “block” contains data, and blocks are linked in a chronological “chain.”
Blockchain technology is an advanced database mechanism that allows transparent information sharing within a business network. A blockchain database stores data in blocks that are linked together in a chain. The data is chronologically consistent because you cannot delete or modify the chain without consensus from the network. As a result, you can use blockchain technology to create an unalterable or immutable ledger for tracking orders, payments, accounts, and other transactions. The system has built-in mechanisms that prevent unauthorized transaction entries and create consistency in the shared view of these transactions.
What Is a Blockchain?
A blockchain is a distributed database or ledger shared across a computer network’s nodes. They are best known for their crucial role in cryptocurrency systems, maintaining a secure and decentralized record of transactions, but they are not limited to cryptocurrency uses. Blockchains can be used to make data in any industry immutable—meaning it cannot be altered.
Since a block can’t be changed, the only trust needed is at the point where a user or program enters data. This reduces the need for trusted third parties, such as auditors or other humans, who add costs and can make mistakes.
How Does Blockchain Technology Work?
Blockchain technology operates as a decentralized, secure, and transparent ledger that ensures data integrity.
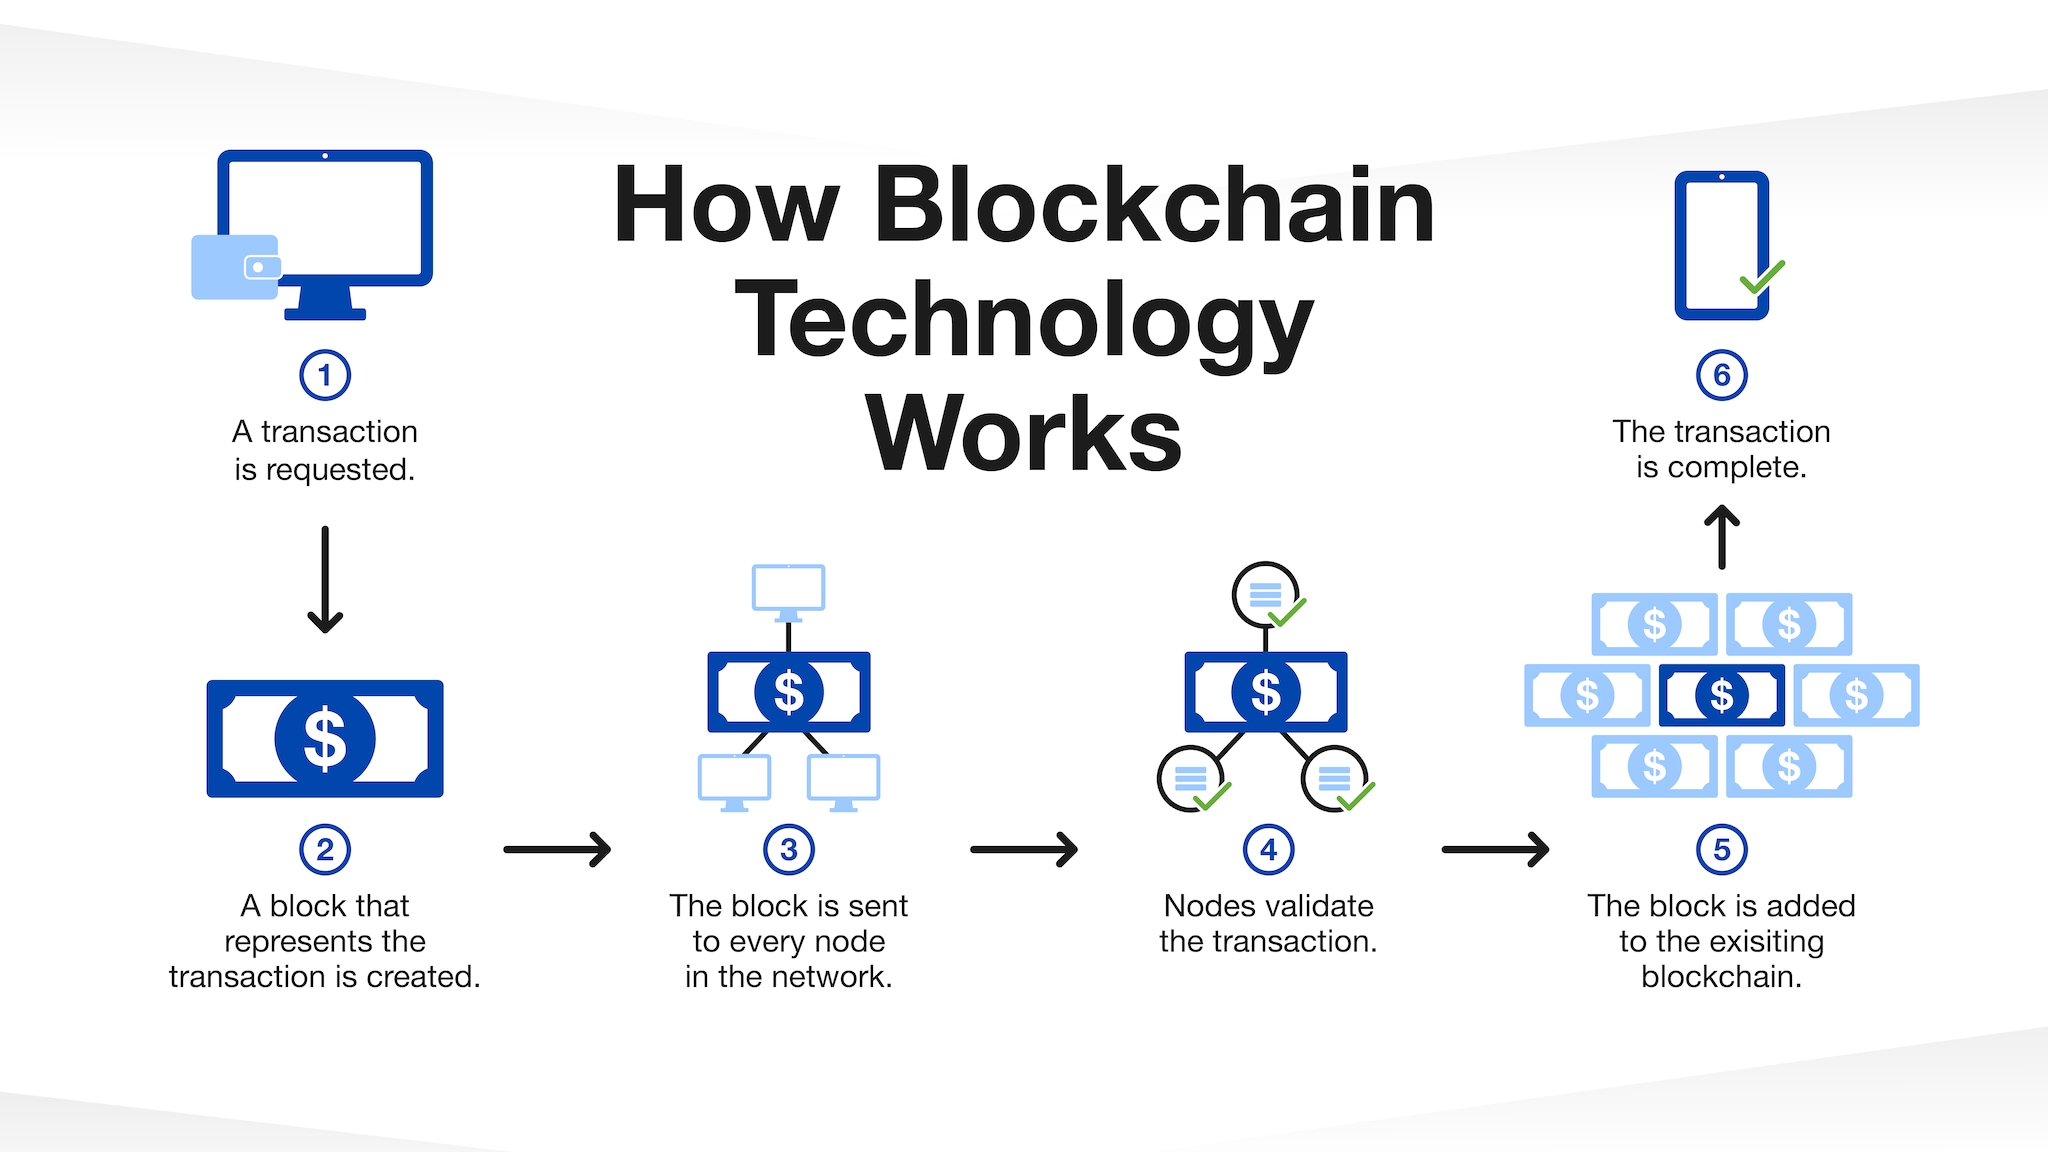
Here’s a breakdown of how it functions:
1. A Transaction Is Initiated
- A user initiates an action, such as sending cryptocurrency, updating a record, or triggering a smart contract.
- Example: Alice sends 1 Bitcoin to Bob.
2. The Transaction Is Broadcasted to the Network
- The transaction is sent to the blockchain’s peer-to-peer network, which consists of multiple nodes (computers).
- Each node receives the transaction and prepares to validate it.
3. Transaction Is Verified
- Nodes in the network use a consensus mechanism to validate the transaction. Common mechanisms include:
- Proof of Work (PoW): Nodes solve complex mathematical puzzles to verify transactions.
- Proof of Stake (PoS): Validation is based on the number of tokens a participant holds.
- The verification ensures that Alice has the required balance and that the transaction isn’t fraudulent.
4. Transaction Is Grouped into a Block
- Once verified, the transaction is bundled with others occurring around the same time into a block.
- Each block includes:
- The transaction data.
- A unique identifier called a hash.
- The hash of the previous block, linking it to the chain.
5. The Block Is Added to the Blockchain
- After consensus is reached, the block is added to the existing blockchain.
- The blockchain updates across all nodes simultaneously, ensuring all participants have an identical copy of the ledger.
6. Transaction Becomes Immutable
- Once the block is added, the data becomes tamper-proof.
- Altering any block would require changing all subsequent blocks and gaining consensus across the network—a virtually impossible task.
7. Completion of Transaction
- The transaction is finalized, and Bob receives the 1 Bitcoin sent by Alice.
- The blockchain ledger reflects the updated balance, visible to all participants for transparency.
What are the features of blockchain technology?
Blockchain technology has the following main features:
Decentralization
Decentralization in blockchain refers to transferring control and decision making from a centralized entity (individual, organization, or group) to a distributed network. Decentralized blockchain networks use transparency to reduce the need for trust among participants. These networks also deter participants from exerting authority or control over one another in ways that degrade the functionality of the network.
Immutability
Immutability means something cannot be changed or altered. No participant can tamper with a transaction once someone has recorded it to the shared ledger. If a transaction record includes an error, you must add a new transaction to reverse the mistake, and both transactions are visible to the network.
Consensus
A blockchain system establishes rules about participant consent for recording transactions. You can record new transactions only when the majority of participants in the network give their consent.
What are the key components of blockchain technology?
Blockchain architecture has the following main components:
A distributed ledger
A distributed ledger is the shared database in the blockchain network that stores the transactions, such as a shared file that everyone in the team can edit. In most shared text editors, anyone with editing rights can delete the entire file. However, distributed ledger technologies have strict rules about who can edit and how to edit. You cannot delete entries once they have been recorded.
Smart contracts
Companies use smart contracts to self-manage business contracts without the need for an assisting third party. They are programs stored on the blockchain system that run automatically when predetermined conditions are met. They run if-then checks so that transactions can be completed confidently. For example, a logistics company can have a smart contract that automatically makes payment once goods have arrived at the port.
Public key cryptography
Public key cryptography is a security feature to uniquely identify participants in the blockchain network. This mechanism generates two sets of keys for network members. One key is a public key that is common to everyone in the network. The other is a private key that is unique to every member. The private and public keys work together to unlock the data in the ledger.
What are the types of blockchain networks?
There are four main types of decentralized or distributed networks in the blockchain:
Public blockchain networks
Public blockchains are permissionless and allow everyone to join them. All members of the blockchain have equal rights to read, edit, and validate the blockchain. People primarily use public blockchains to exchange and mine cryptocurrencies like Bitcoin, Ethereum, and Litecoin.
Private blockchain networks
A single organization controls private blockchains, also called managed blockchains. The authority determines who can be a member and what rights they have in the network. Private blockchains are only partially decentralized because they have access restrictions. Ripple, a digital currency exchange network for businesses, is an example of a private blockchain.
Hybrid blockchain networks
Hybrid blockchains combine elements from both private and public networks. Companies can set up private, permission-based systems alongside a public system. In this way, they control access to specific data stored in the blockchain while keeping the rest of the data public. They use smart contracts to allow public members to check if private transactions have been completed. For example, hybrid blockchains can grant public access to digital currency while keeping bank-owned currency private.
Consortium blockchain networks
A group of organizations governs consortium blockchain networks. Preselected organizations share the responsibility of maintaining the blockchain and determining data access rights. Industries in which many organizations have common goals and benefit from shared responsibility often prefer consortium blockchain networks.
What are blockchain protocols?
Blockchain protocols are the foundational rules, standards, and structures that govern the operation of a blockchain network. They define how data is created, validated, and transmitted across the network, ensuring that all participants (nodes) can interact and agree on the state of the blockchain. Think of blockchain protocols as the “blueprint” or “operating system” for blockchain technology.
Key Functions of Blockchain Protocols
- Define Consensus Mechanisms:
Blockchain protocols determine how the network reaches agreement on transactions and data validity. Common mechanisms include:
- Proof of Work (PoW): Used by Bitcoin; relies on solving complex mathematical problems.
- Proof of Stake (PoS): Used by Ethereum 2.0; validators are chosen based on their stake in the network.
- Set Data Structures:
Protocols specify how data is stored and organized within the blockchain. For example, blocks contain transaction data, timestamps, and hashes linking them to previous blocks. - Enable Decentralization:
Protocols ensure that no single entity controls the network, distributing control across nodes. - Enforce Security:
Blockchain protocols use cryptographic methods to secure transactions and prevent tampering. - Facilitate Scalability:
They define how the network handles increasing transaction loads and ensures seamless scaling as more users join.
Types of Blockchain Protocols
- Public Blockchain Protocols:
- Open to anyone for participation and validation.
- Examples:
- Bitcoin Protocol: Focused on decentralized currency and secure peer-to-peer transactions.
- Ethereum Protocol: Supports smart contracts and decentralized applications (dApps).
- Private Blockchain Protocols:
- Restricted access for specific participants within an organization or consortium.
- Example:
- Hyperledger Fabric: Designed for enterprise use, offering customizable access permissions.
- Consortium Blockchain Protocols:
- Semi-decentralized and governed by a group of organizations.
- Example:
- R3 Corda: Tailored for financial institutions, focusing on security and privacy.
- Sidechain Protocols:
- Allow interoperability between blockchains by connecting a secondary chain to a main chain.
- Example:
- Polygon Protocol: Improves Ethereum’s scalability and transaction speed.
Popular Blockchain Protocols and Their Use Cases
| Protocol | Type | Use Case |
| Bitcoin | Public | Cryptocurrency and store of value |
| Ethereum | Public | Smart contracts and decentralized applications |
| Hyperledger | Private | Enterprise solutions for supply chain, finance |
| Ripple (XRP) | Consortium | Cross-border payments and remittance |
| Polkadot | Public | Interoperability between blockchains |
| Stellar | Public | Cross-border payments for individuals |
What are the benefits of blockchain technology?
Blockchain technology brings many benefits to asset transaction management. We list a few of them in the following subsections:
Advanced security
Blockchain systems provide the high level of security and trust that modern digital transactions require. There is always a fear that someone will manipulate underlying software to generate fake money for themselves. But blockchain uses the three principles of cryptography, decentralization, and consensus to create a highly secure underlying software system that is nearly impossible to tamper with. There is no single point of failure, and a single user cannot change the transaction records.
Improved efficiency
Business-to-business transactions can take a lot of time and create operational bottlenecks, especially when compliance and third-party regulatory bodies are involved. Transparency and smart contracts in blockchain make such business transactions faster and more efficient.
Faster auditing
Enterprises must be able to securely generate, exchange, archive, and reconstruct e-transactions in an auditable manner. Blockchain records are chronologically immutable, which means that all records are always ordered by time. This data transparency makes audit processing much faster.
What is the difference between Bitcoin and blockchain?
Bitcoin and blockchain might be used interchangeably, but they are two different things. Since Bitcoin was an early application of blockchain technology, people inadvertently began using Bitcoin to mean blockchain, creating this misnomer. But blockchain technology has many applications outside of Bitcoin.
Bitcoin is a digital currency that operates without any centralized control. Bitcoins were originally created to make financial transactions online but are now considered digital assets that can be converted to any other global currency, like USD or euros. A public Bitcoin blockchain network creates and manages the central ledger.
Bitcoin network
A public ledger records all Bitcoin transactions, and servers around the world hold copies of this ledger. The servers are like banks. Although each bank knows only about the money its customers exchange, Bitcoin servers are aware of every single Bitcoin transaction in the world.
Anyone with a spare computer can set up one of these servers, known as a node. This is like opening your own Bitcoin bank instead of a bank account.
Bitcoin mining
On the public Bitcoin network, members mine for cryptocurrency by solving cryptographic equations to create new blocks. The system broadcasts each new transaction publicly to the network and shares it from node to node. Every ten minutes or so, miners collect these transactions into a new block and add them permanently to the blockchain, which acts like the definitive account book of Bitcoin.
Mining requires significant computational resources and takes a long time due to the complexity of the software process. In exchange, miners earn a small amount of cryptocurrency. The miners act as modern clerks who record transactions and collect transaction fees.
All participants across the network reach a consensus on who owns which coins, using blockchain cryptography technology.
Conclusion
At Hubtech Limited, we understand the transformative potential of blockchain technology and its ability to revolutionize industries like finance, supply chain, healthcare, and more.
Whether you’re exploring public blockchain solutions for transparency or private protocols for enterprise applications, understanding how these protocols work is key to unlocking their full potential. Hubtech Limited is committed to guiding businesses through this journey by providing expert insights, tailored solutions, and cutting-edge technology.
Let us help you harness the power of blockchain protocols to streamline operations, enhance trust, and secure your business for the future. Reach out to us today to learn more!

